|
GM. This is The Financial Darwin Awards, the only financial newsletter with a 100% loss rate. Everything that hurt this week was on the calendar. Nvidia's print was scheduled. Jackson Hole was scheduled. The PayPal bid had been public for weeks. None of it was secret, and four people still finished on the wrong side of all of it. Four traders lost $97,906 between them, and not one of them was ambushed. The traders are composites. The moves are not. Here's what we've got today:
THIS WEEK'S DAMAGE REPORT 📊
The first number is the sum of the four stories below. The second is real: PayPal closed Friday at $53.66, down 12.71%, after Advent International and Stripe walked away from a takeover reported at roughly $50 billion to $53 billion.
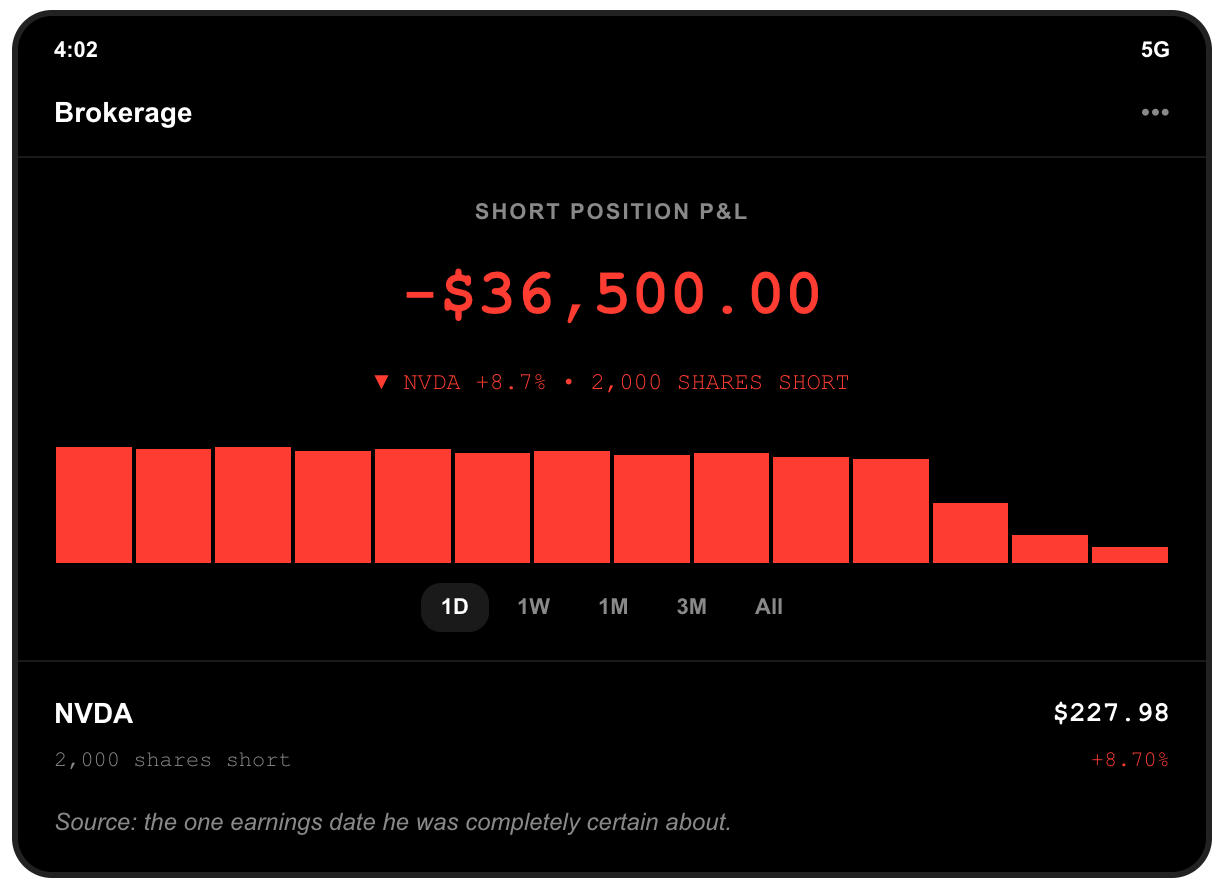
DARWIN AWARD OF THE WEEK 🏆 Every issue we crown the single worst financial decision on the internet. This week it goes to a man who read the setup correctly and drew precisely the wrong conclusion from it. Here's the setup. u/it_cant_double_again was short 2,000 shares of Nvidia going into Wednesday evening, about $419,000 of stock. His thesis was not stupid. Revenue had grown so fast for so long that the comparisons were becoming absurd. Nothing compounds off a base that big forever, he wrote. That was the entire trade. Wednesday after the close, Nvidia reported $96.2 billion of revenue for the quarter, up 106% from a year ago. Data center alone was $89.0 billion. Then management guided the current quarter to $108.0 billion, plus or minus 2%. It compounded off the base that big, and then told everyone it would do it again. The stock closed Thursday at $227.98, up about 8.7%, which is roughly $18.25 a share. Short 2,000 shares, that is $36,500 in one session. He was right that the growth rate has to break. He was wrong that it had to break this quarter.
Here's the thing. A short is not a view, it is a view with a deadline. Being early and being wrong produce identical brokerage statements. The trade needed the slowdown to arrive inside one specific ninety day window, and the company instead guided to about 89% growth for the next one. Gross margin held at 75.0%, up from 72.4% a year earlier, though the company did flag rising memory costs ahead. That is the part worth understanding, and it cost him $36,500 to learn that a correct thesis with the wrong date is simply a wrong thesis.
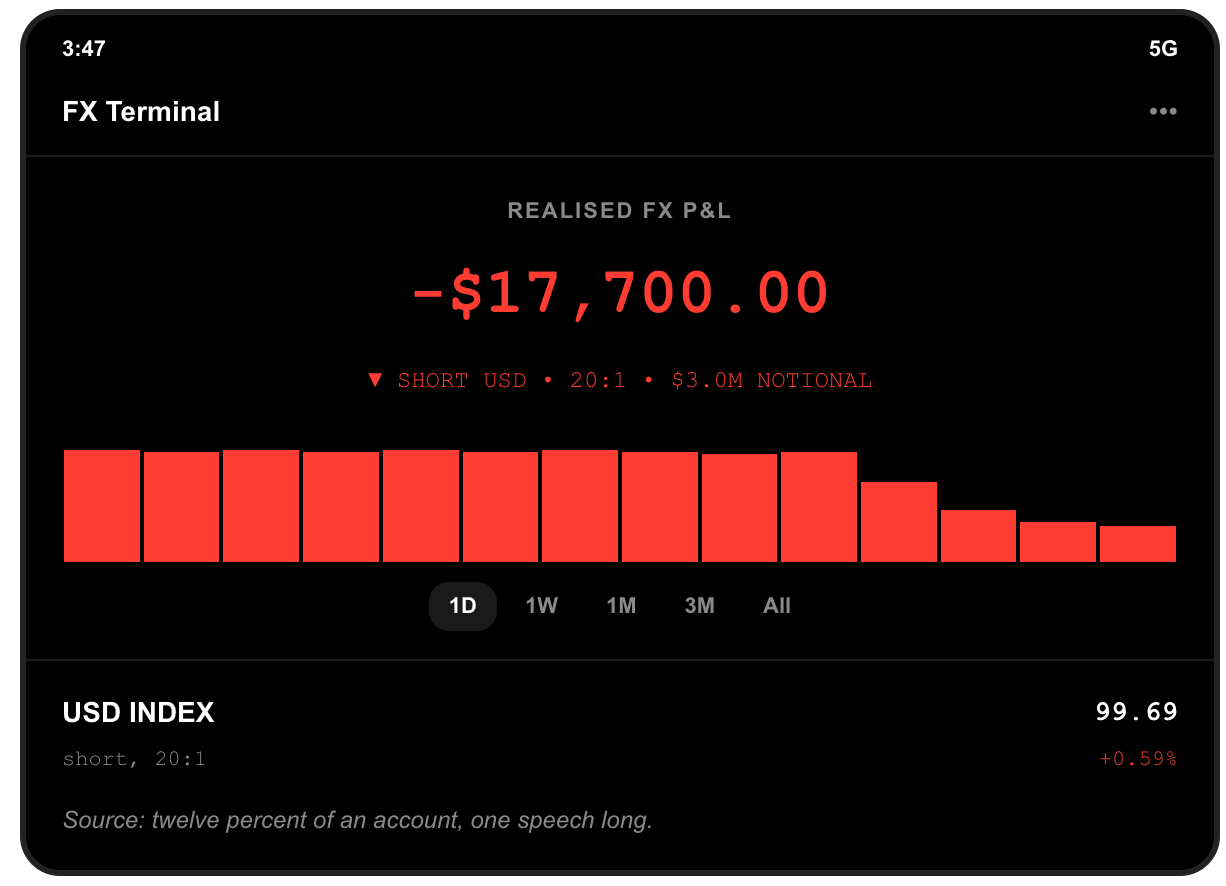
THIS WEEK'S CASUALTIES 💀 Not everybody can be Darwin Award of the week. These three gave it a real shot. Let's run through the tape. Casualty #1: The Man Who Shorted A Stranger u/three_cuts_priced_in was short the US dollar, $3,000,000 of notional standing on $150,000 of margin, twenty to one. The trade had worked all summer. Cuts were coming, the dollar would bleed, everybody agreed. Then a brand new Federal Reserve chair gave his first Jackson Hole speech on Friday. Kevin Warsh called the 2% inflation target "firm, fixed," noted that PCE inflation was running at 3.7% a year, and said the Fed would "have work to do." Odds of a September hike went from about 35% before the speech to roughly 57% after it, and the dollar posted its best session in about two and a half months. The dollar index closed up 0.59% at 99.69, which at twenty to one is almost 12% of his account in an afternoon. $3,000,000 of notional, moved 0.59% the wrong way, is $17,700. He had a firm view on interest rates and no view at all on the man who sets them.
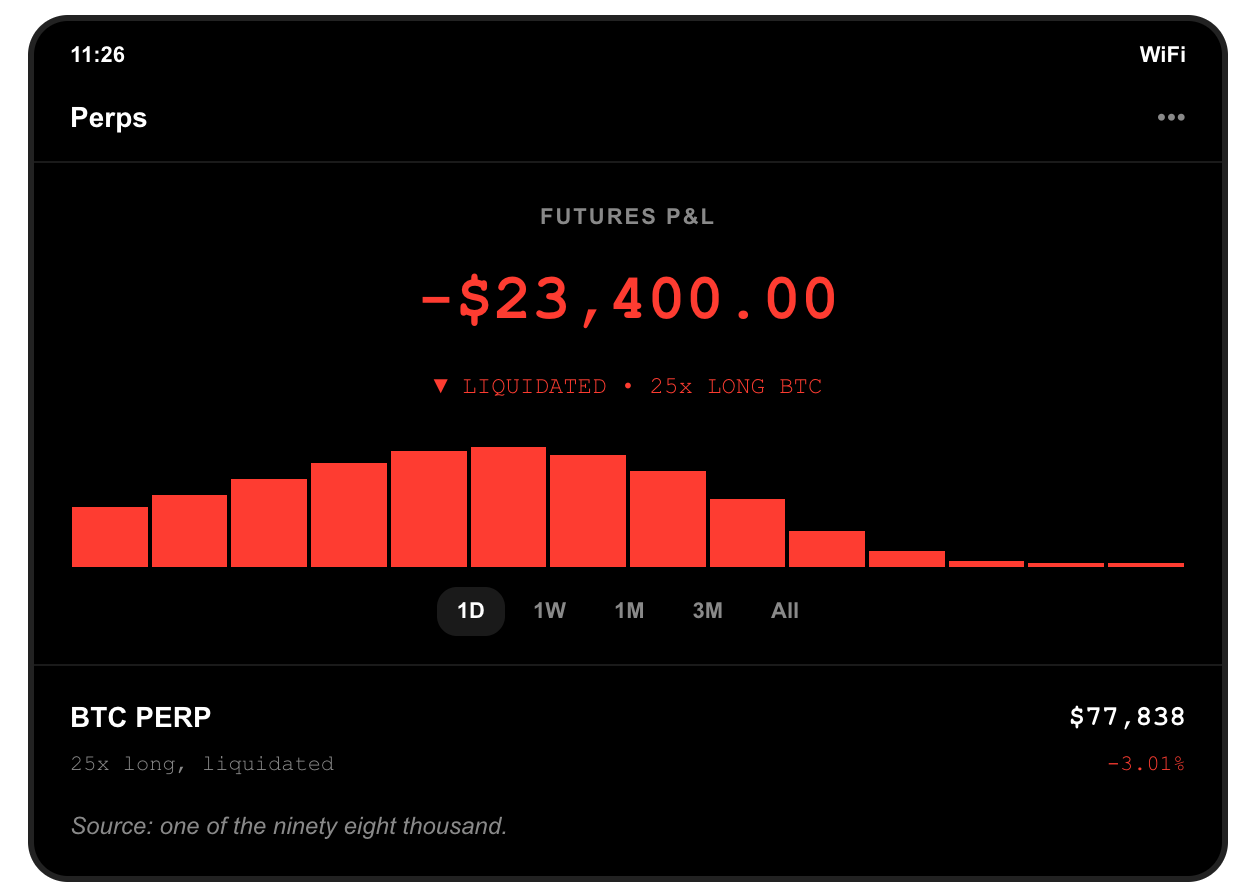
Casualty #2: The 81,000 Guy u/bought_the_81k_candle opened a long bitcoin perpetual on Friday morning, as the price pushed above $81,000. He used twenty five times leverage, $23,400 of margin standing behind $585,000. At that leverage the position dies on a move of roughly 4%. Bitcoin closed the day at $77,838, down 3.01%. From the level he bought, that is a fall of about 3.9%, and 3.9% times twenty five is the entire position. Roughly $488 million was liquidated across crypto on Friday, catching nearly 98,000 accounts, most of them long. The nine day run of spot bitcoin ETF inflows that had carried the rally, $3.04 billion between August 17 and 27, snapped the same day with a $202 million outflow. He was not liquidated by a crash. He was liquidated by an ordinary 3% session.
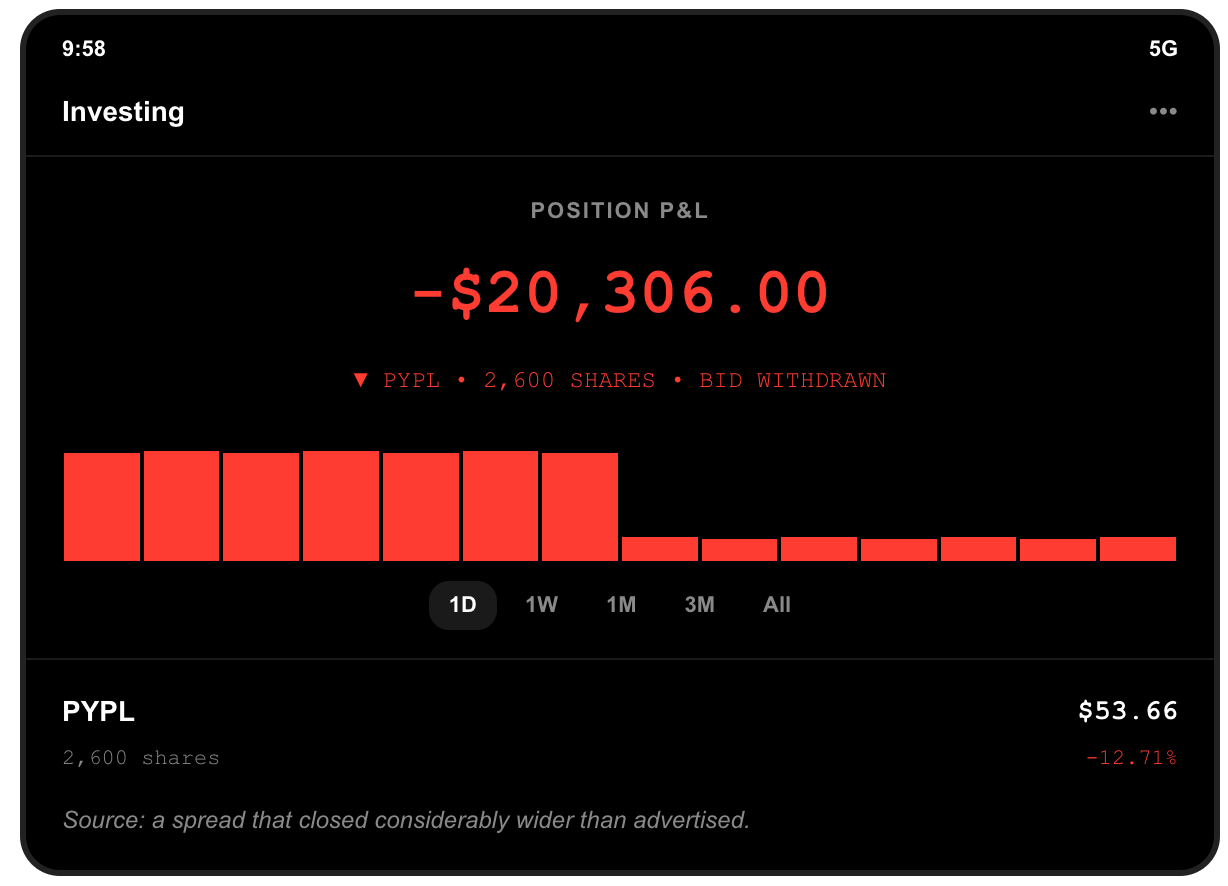
Casualty #3: The Riskless Arbitrageur u/arb_is_riskless owned 2,600 shares of PayPal, about $159,800 at Thursday's close. He was not investing in the payments business. He was collecting the last few dollars of a takeover. Advent International and Stripe had bid $60.50 a share for the company, in a deal reported at roughly $50 billion to $53 billion. PayPal closed Thursday at $61.47, above the offer, because the market expected the price to be raised. On Friday the consortium walked away. PayPal closed at $53.66, down $7.81, and the riskless spread cost him $20,306. Bernstein had already noted that PayPal management was unlikely to accept anything that was not meaningfully above $70. That was the trade working exactly as designed, right up to the morning it stopped being a trade at all.
THIS WEEK BY THE NUMBERS 📊 We track the data because the data is funnier than anything we could make up.
The Nvidia print and the Jackson Hole speech were both on the calendar weeks ahead. Everything else on this page is what they cost four people who did not leave any room.
BITE-SIZED COPIUM FOR THE ROAD 🍪 The best part of any loss thread isn't the screenshot. It's the comments section. Here are this week's greatest hits.
Translation: everybody held a reasonable opinion. Nobody held a reasonable amount of room to be wrong about it.
DUMB MEMES 🤣 Every newsletter needs a meme section. Ours just hits different when the date of the damage was printed in advance.
POV: you were short the one company that guided higher
u/three_cuts_priced_in, meeting the new Fed chair If you laughed, you're coping. If you didn't laugh, go and look at what is on next week's calendar. See you next issue. Same calendar. Different casualties. Traders and P&L screenshots are satirical composites. Market data, earnings figures and price moves are real and dated August 26 to 28, 2026. Not financial advice. Obviously. Look at us. Stay liquid, |
Everything that hurt this week was on the calendar.
A short that was right about the arithmetic and wrong about the month, a currency trade that met a brand new Fed chair, and a takeover that stopped being one.